
The most resilient retail brands of 2026 aren't competing on price or speed. They're competing on cultural relevance – and the data shows it's working. A look at what separates a brand from a habit.

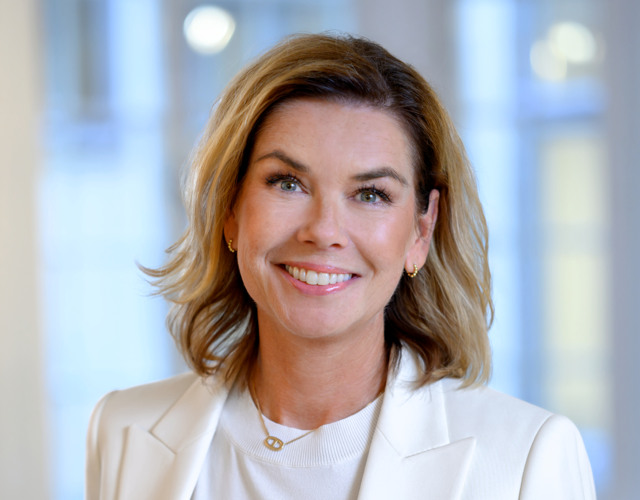
Head of Company
Sofia Larsen är redaktör för Svensk Handel Insights. Hon har 15 års bakgrund från retail- och varumärkesvärlden, med tidigare roller på Acne Studios och H&M. Idag bevakar hon skärningspunkten mellan kultur och kommers — och vad nordiska varumärken kan lära världen.
Reading time
4 min
Ten years ago, retail strategy was a logistics problem dressed up as a marketing one. Faster shipping, lower prices, smoother checkout. The winners would be whoever optimized hardest.
That playbook still works. But it doesn’t win anymore.
Walk into any boardroom in Stockholm, Copenhagen, or Berlin right now and you’ll hear a different conversation. It’s no longer about being the cheapest or the quickest. It’s about being the brand people actually want to be associated with — the one they post about, recommend unprompted, defend in arguments. The one that makes them feel like part of something. That’s culture. And culture is now the most defensible moat in commerce.
A study from Kantar earlier this year tracked 200 Nordic consumer brands across five years of growth, churn, and pricing power. The findings were uncomfortable for anyone still selling on margin alone:
Brands that consumers described as “culturally relevant” – meaning the brand felt connected to something larger than the product itself — grew 3.2x faster than category averages. They also retained customers 2x longer and could sustain price premiums of 17–24% without losing share.
The kicker: this gap is widening, not closing. As AI flattens the experience layer of e-commerce (better recommendations, smoother checkout, faster delivery – for everyone), the only thing left to differentiate on is meaning.
The word gets thrown around loosely, so let’s be specific. Culture isn’t a brand campaign. It isn’t a TikTok strategy. It isn’t a sustainability report. Those are outputs. Culture is what happens when a brand consistently shows up with a clear point of view, in places its customers already care about, with content and products that feel like contributions rather than interruptions.
The packaging hasn’t changed in 20 years. The product range expands slowly and deliberately. The stores read like reading rooms. Every touchpoint says the same thing without saying it out loud: we take craft seriously, and so should you. That’s culture as commerce.
Or Patagonia. The “Don’t buy this jacket” campaign – now over a decade old — wasn’t a stunt. It was a worldview. Customers didn’t buy less. They bought more, because Patagonia had made itself the obvious choice for a specific kind of person.
Or Arket, Daily Paper, Eytys, Filippa K. None of these brands are competing on Amazon’s terms. They’re competing on identity terms. And it works.
Or Arket, Daily Paper, Eytys, Filippa K. None of these brands are competing on Amazon’s terms. They’re competing on identity terms. And it works.

The wrong way to do this
The trap most brands fall into is treating culture as a layer on top of an existing strategy. They keep the same product, the same pricing, the same operations – and bolt on a “cultural moment” via a collaboration, a pop-up, or a celebrity endorsement.
This almost always fails. Not because collaborations are bad, but because audiences can spot when the values are decoration rather than direction. The collab does numbers for one quarter, then everyone moves on, and the brand is right back where it started —– competing on logistics.
The brands winning at this don’t bolt culture on. They build the business from it. The product roadmap, the hiring, the supply chain, the retail experience, the customer service tone — all of it flows from a clearly articulated worldview. That’s why it feels coherent. Because it is.
What this means for D-Congress 2026
This is why the theme this year is “Shaping Culture – Transforming Commerce”. It’s not a tagline. It’s a working hypothesis: that the next decade of retail will be defined less by who has the best supply chain and more by who has the strongest point of view.
Over two days at Svenska Mässan, you’ll hear from the people doing this in practice. Founders who’ve built brands that customers tattoo on their bodies. Marketers who’ve stopped chasing trends and started setting them. Operators who treat their cultural footprint as seriously as their carbon footprint.
If you came to D-Congress last year for the logistics talks, come this year for the brand talks. The center of gravity has shifted.
The transactional layer of commerce is becoming a commodity. The cultural layer is where the value is moving.
That’s where you want to be.
The most resilient retail brands of 2026 aren't competing on price or speed. They're competing on cultural relevance – and the data shows it's working. A look at what separates a brand from a habit.
The most resilient retail brands of 2026 aren't competing on price or speed. They're competing on cultural relevance – and the data shows it's working. A look at what separates a brand from a habit.
The most resilient retail brands of 2026 aren't competing on price or speed. They're competing on cultural relevance – and the data shows it's working. A look at what separates a brand from a habit.
The most resilient retail brands of 2026 aren't competing on price or speed. They're competing on cultural relevance – and the data shows it's working. A look at what separates a brand from a habit.